On Florida’s Suncoast, similar asking prices can represent very different ownership experiences. A bayfront house near Longboat Key, a condominium overlooking the Gulf, and a newly built Sarasota-area home may all offer appealing locations, but their insurance, maintenance, association obligations, and day-to-day lifestyles can vary sharply.
Buyers weighing those choices can benefit from area-specific guidance. Longboat Key real estate agents Bruce Myer Group is a Sarasota-area real estate team whose website covers luxury homes, waterfront properties, condominiums, and new-construction opportunities. With service across Longboat Key, Bird Key, Lido Key, Siesta Key, and Sarasota, Bruce Myer Group brings a useful local perspective to comparisons in which a single street, building, or canal can change a property’s practical value.
Start With the Lifestyle You Want
Before comparing finishes, square footage, or monthly payments, define how the home should serve your life. A waterfront residence can suit buyers who place a high value on water views, boating, private outdoor space, or direct access to a dock. A condo may fit someone who wants amenities and less individual exterior upkeep. New construction can appeal to buyers seeking contemporary layouts, new systems, and builder warranty coverage.
A Quick Lifestyle Checklist
- How often will you use the property, full-time, seasonally, or as a second home?
- Is boat access, beach proximity, or a water view essential?
- How much personal maintenance are you comfortable managing?
- Will rental flexibility matter now or later?
- Do amenities, privacy, walkability, parking, or storage rank highest?
Compare the Full Monthly Cost
The mortgage payment is only one line in the ownership budget. Create the same simple comparison list for each finalist property, then update it as quotes and documents arrive.
- Purchase price, down payment, principal, and interest
- Property taxes and any applicable community development district charges
- Homeowners, condo, wind, and flood insurance
- HOA or condominium fees
- Utilities, landscaping, pool care, and routine repairs
- Potential roof, exterior, dock, seawall, or building-related costs
For each home, write down the estimated monthly carrying cost after adding every recurring item. Then keep a separate reserve for irregular expenses. This approach makes it easier to see whether a lower-priced waterfront home may actually cost more to own than a newer inland alternative.
Check Flood Risk and Insurance Before Making an Offer
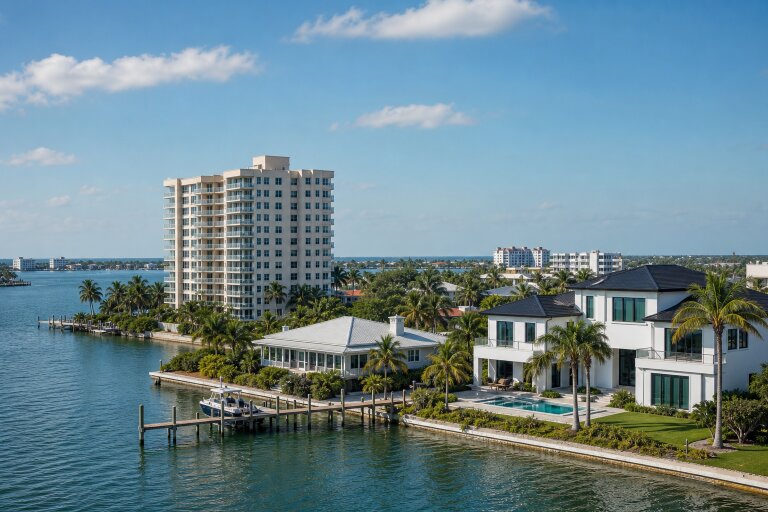
Coastal living requires property-level due diligence. Review the flood zone and elevation information, when available, visible drainage conditions, prior flood-related disclosures, and the cost of insurance before the inspection period ends. FEMA explains that flood zones and maps help homeowners understand local exposure, while also noting that every property carries some degree of flood risk.
- Do not rely on a listing description to determine insurance needs.
- Ask whether an elevation certificate is available.
- Request real insurance quotes early, not just estimates.
- Confirm lender requirements and review deductibles, exclusions, and limits.
Study Waterfront Features Beyond the View
Not all waterfront is equally usable. A broad view may be exceptional, but a buyer who wants a boat should also investigate water depth at low tide, fixed-bridge clearance, distance to open water, and the route from the property to the Gulf. Canal, bay, open water, and lake frontage each create different opportunities and responsibilities.
Inspect the dock, boat lift, seawall, shoreline condition, permits, and any known dredging needs. When significant marine improvements are involved, a qualified dock inspector, marine contractor, or engineer can help clarify the condition and likely future work. Storm preparation should also be part of the decision, particularly for exterior equipment and waterfront structures.
Review Condo Documents With Care
A condo buyer purchases a unit and also accepts a share of the association’s financial responsibilities. Request the budget, financial statements, reserve information, insurance summary, recent board minutes, rules, rental policies, pet restrictions, parking assignments, and any notices involving repairs or special assessments.
Florida buyers should also understand the milestone inspection and structural reserve study requirements for qualifying residential condominium and cooperative buildings. Those records can help a buyer ask informed questions about building condition, reserve planning, and projects that could affect future assessments.
Look Past the New-Construction Model
A polished model home demonstrates a builder’s design vision, but it may not show the final price or exact features of the home being purchased. Compare the base price with upgrades, lot premiums, appliance packages, landscaping, and closing costs. Confirm what is included in the contract, the projected completion schedule, and the terms that apply if the schedule changes.
A quick-move-in home is typically further along or complete, while a production build follows a builder’s established plans and selections. A custom home generally offers more design flexibility, but can involve a more individualized planning process. Regardless of type, consider an independent inspection and, when timing permits, a pre-drywall inspection.
Compare Maintenance Responsibilities
- Waterfront home: The owner may be responsible for the roof, windows, pool, landscaping, dock, seawall, and storm preparation.
- Condo: The association may manage common exterior elements, but the owner remains responsible for the interior, personal insurance, and association charges.
- New construction: Early maintenance may be lighter, yet warranties have limits, and future landscaping, HOA obligations, and system upkeep still require planning.
Think About Resale Value
Future buyers may prioritize features differently from you. Usable boat access can matter more than waterfront footage alone. A building with clear financial records and well-understood reserves may be easier to evaluate than one with unanswered questions. In many Suncoast locations, views, assigned parking, storage, outdoor space, walkability, and rental rules can also affect buyer interest.
Compare recent closed sales with similar locations, property types, and conditions rather than relying only on active listings or automated estimates. The most useful comparison is usually the one that accounts for the details a buyer can actually use.
Questions to Ask Before Choosing a Property
- What is the full monthly cost after taxes, insurance, fees, and upkeep?
- What flood and wind-related insurance information is available?
- Which repairs or replacements may be needed within five years?
- Are special assessments planned, proposed, or recently discussed?
- What rules apply to rentals, pets, boats, parking, and renovations?
- What distinguishes this property from nearby alternatives?
A Simple Five-Step Comparison Process
- Define priorities: Rank water access, privacy, amenities, location, and low maintenance.
- Build a complete budget: Add every recurring and likely nonrecurring cost.
- Review risks: Check insurance, flood exposure, structural records, and waterfront improvements.
- Compare alternatives: Evaluate similar properties in the same general area and price range.
- Use qualified professionals: Complete inspections and document review before contingencies expire.
Final Takeaway
Waterfront homes, condos, and new-construction properties can all be strong choices on Florida’s Suncoast. The best fit depends on how you will use the property, which responsibilities you want to retain, and whether the complete cost remains comfortable over time. Compare the full numbers, verify the major details, and choose the home that supports both your lifestyle and your long-term plans.